Understanding ALTA Table A Item 3: Flood Zone Classification
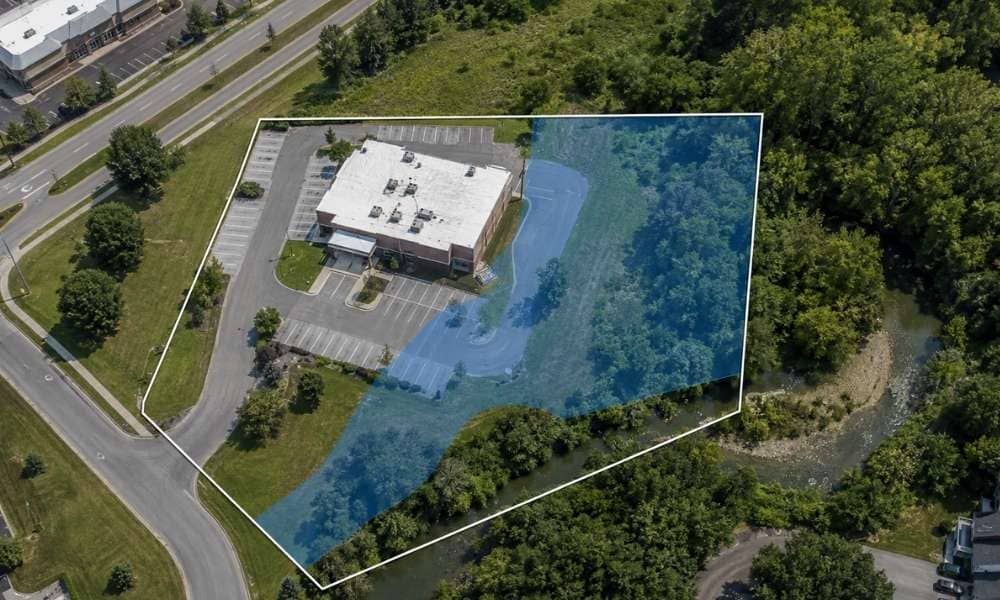
Figure A Item 3 assigns a flood zone designation on an ALTA/NSPS Land Title Survey. The sum of many buyers and lenders underappreciates it. This explains the parameters of Item 3, how it appears on the drawing, and what the bounds are.
What ALTA Table A Item 3 Actually Covers
Item 3 is one of the optional boxes on an ALTA/NSPS survey order. The client can pick this box and the surveyor will put the flood zone designation on the drawing.
Item 3 deals with classification only. It is not a study in flood risk. The surveyor will not assess the probability of the building flooding. The surveyor will not assess the potential insurance claim should a flood occur.
The standard for 2026 links this classification to the national Flood Insurance Rate Maps. These are known as FIRM panels. If the survey location is not covered by FEMA, then the survey can use a state or local map.
Item 3 is in Table A because not all surveys require it. Remote rural lots away from water may not need it. A commercial parcel adjacent to a mapped floodplain needs it. The standard does not require it; it leaves that up to the client, lender, and title company.
How the Flood Zone Gets Plotted on the Survey
Category and plotting. Are not the same step. Category is the zone name. A zone might be called Zone A, or that zone might be called Zone X. Plotting is where that zone is on the drawing.
The 2026 wording states for the flood zone to be represented by scaled map position and graphic plotting. The surveyor begins with the property limits established from the field work. The flood map boundary being laid over the existing drawing, at the same scale.
Two geospatial data sets are referenced here. The legal boundary of the parcel is defined by monuments and field measurements. The flood map boundary is defined by FEMA or the appropriate local source. Lining these two data sets up indicates what proportion of a parcel’s land area is within an identified floodplain, and the location of the boundary line on each parcel.
Do not get this confused with a flood elevation certificate. #3 does not require ground elevations. It does not compare the site to a base flood elevation. That would be part of a different survey scope.
What the Survey Shows, and What It Does Not Establish
This is where the line of the flood map hits on a piece of ground; number 3. This does not give you all information about the risks of flooding on that ground.
This is a map that FEMA (or other mapping agency) produced. It is not the surveyors line for that flood zone, it is an existing line (not surveyed) that has been positioned on the property. The surveyor identified the line and laid it out on the property. Maps become outdated. A levee or drainage project can alter the condition after the map has been produced. This is not reflected in a survey.
You could have a property outside a mapped flood zone and have it flood; zoning is only an indicator of flood likelihood. You could have a property inside a flood zone and have it be graded or drained so that the true onsite risk is minimal. Item 3 only answers the mapping question. It does not answer the risk question.
Flood insurance answers to the question “Buyer?” should be considered a single data point. The same is true for the lenders who determine flood insurance requirements. Item 3 does support other steps. Contact an agent. Go to FEMA themselves. Item 3 does not replace these other steps.
Why the Source of the Flood-Zone Classification Matters
A flood zone map on a page means nothing without a source. The 2026 standard mandates that the surveyor identify the source map. That source is either a federal FIRM panel number and date, or a state or local map that applies in place of current FEMA coverage.
By naming the source it leaves open to anyone to verify the original map. It also protects from confusion as the maps are reclassified. FEMA updates the flood maps at its own pace. A classification obtained from an older panel could be different from the current.
Item 3 is most effective where the classification is associated with a named source and date, and it is revealing to pinpoint exactly how the property relates to that boundary that has been mapped out. A flood zone label alone, where no source is provided, is more difficult for a lender, insurer or buyer to verify themselves.
When to Include Item 3 in an ALTA Survey Order
Item 3 is applicable for the majority of properties in proximity to waterways. It is also compatible with properties located within an established mapped floodplain, as well as other transactions that may involve flood insurance. It is routinely used in commercial transactions and would typically be ordered by lenders.
Discuss with the surveyor prior to fieldwork. Table A items are selected in advance. Incorporating them at a later date normally results in change orders and an increase in fee. Notify the lender and title company early. Otherwise a survey order conflicts with the entire transaction.
Item 3 wording, like all the others on Table A, as far as the surveyor and client wish to agree. 2026 of the ALTA handbook has established this is still the case. The selection from Table A and detailed wording is still the subject for compromise in the agreement of the clients & surveyors. Still, all state & local requirements will need to be satisfied.
Before ordering a survey with Item 3, ask the surveyor a few direct questions.
- Which map source will I use? What’s the panel date?
- Is the flood zone line to be plotted onto my boundary? Or just referred to in the text.
- Are more than one flood zone related to my property? And if applicable, will each zone be identified individually?
- If I do ask for Item 5, is it to get the elevation data, or would I be asking that in a different discussion to the engineer?
These questions are not meant to substitute for a conversation with an insurance representative. They are designed to ensure the survey addresses the mapping question it is intended to answer.
